Institutional Insights: Goldman Sachs 'All Eyes On The Mid Terms'
THE GOLDMAN TAKE: POLITICAL REALIGNMENT VS. EARNINGS DECELERATION & CRUDE RISK PREMIA
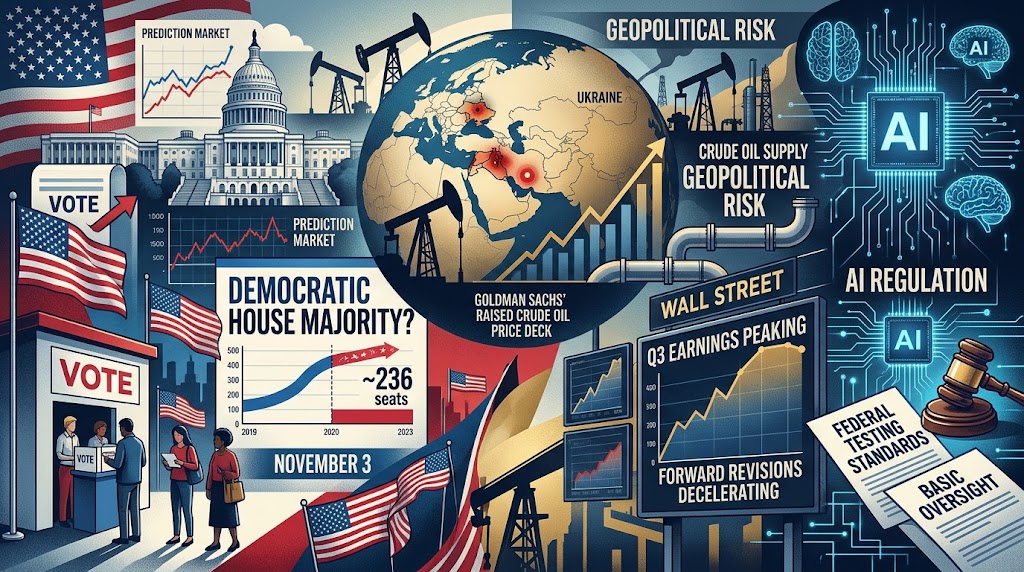
Global markets open the first week of November facing a confluence of political, energy, and fundamental cross-currents. All eyes are on the US Midterm Elections on Tuesday, November 3. Polling indicates national sentiment has shifted 10–11 percentage points toward Democrats, with prediction markets pricing high odds of a Democratic House majority (~236 seats)—a margin of control wider than either party has secured in recent cycles.
While state campaigns raised concerns regarding data center energy draw and infrastructure, GS Research anticipates this issue will recede post-election as state governors refocus and national moratoriums remain improbable. Federal legislative attention is modeled to pivot toward AI regulation, where compromise codifying federal testing standards and basic oversight is plausible, while restrictive legislative caps look unlikely.
Concurrently, Goldman Sachs Commodities Research has raised its crude oil price deck, incorporating a new global supply disruption allowance to reflect persistent Middle East and Ukrainian geopolitical risks. In equity fundamentals, midseason Q3 reporting reveals a key regime transition: earnings growth remains strong, but the rate of earnings acceleration is peaking, establishing a high hurdle for equities as forward earnings revisions decelerate.
COMMODITIES: UPWARD REVISION TO CRUDE OIL PRICE TARGETS
Goldman Sachs raised its near-term and full-year crude oil price projections to account for persistent geopolitical risk premia and an explicit medium-term global supply disruption reserve:
December 2026 Price Targets:
Brent Crude: Raised to $105.00/bbl (from $90.00/bbl).
WTI Crude: Raised to $94.00/bbl (from $81.00/bbl).
2027 Full-Year Averages:
Brent Crude: Lifted to $88.00/bbl (from $80.00/bbl).
WTI Crude: Lifted to $78.00/bbl (from $73.00/bbl).
Structural Catalyst: While Middle East output recovery continues on baseline expectations, heightened threats to shipping corridors and critical energy infrastructure keep embedded risk premia elevated ($25–$27/bbl). An extreme stress scenario where Gulf production remains 3.5M bpd below 2025 levels introduces an upside tail toward $140/bbl Brent.
US EQUITIES MIDSEASON EARNINGS: THE BAR SHIFTS TO RETURN ON CAPITAL
Peak Growth Rate Dynamics: Q3 results demonstrate that while AI capex continues to expand in nominal dollars, the rate of growth of AI capex is peaking.
Hyperscaler Revenue Acceleration: Hyperscaler cloud revenue (Amazon
AMZN, AlphabetGOOGL, MicrosoftMSFT) expanded +54% YoY in Q3, confirming tangible enterprise monetization.Valuation & Revisions Friction: Because institutional length and positioning entered the reporting period elevated, strong headline prints have faced high hurdle rates. While analysts continue to raise forward 12-month earnings estimates, the pace of positive net upward revisions has moderated.
AI Disruption Watch: Q3 management transcripts have heightened investor sensitivity to software disruption risk and competitive margin erosion across broader TMT components.
ASIA-PACIFIC MACRO, CONVICTION LIST & CHINA FINANCIALS
Macro Survey on China Momentum:
GDP & Consumption: Over 50% of survey respondents expect growth momentum and consumption to hold steady, while ~33% project a further deceleration.
Property & Policy: Offshore accounts express relative optimism on property price stabilization vs. cautious onshore sentiment. A conventional PBOC policy rate cut within 6 months is viewed as a close call. Modest CNY appreciation is the baseline consensus.
GS Asia-Pacific Conviction List (November Rebalance):
Additions: Elite Material, Yokohama Rubber, JSW Steel.
Removals: Nan Ya Printed Circuit Board (
NYPCB), Shengyi Technology, Hong Kong Exchanges (HKEX).
China Large-Cap Banks (3Q26 First Take):
Big 5 state-owned lenders outperformed expectations, delivering +16% YoY growth in Pre-Provision Operating Profit (PPOP) and +7% YoY net income growth.
Drivers included stabilizing Net Interest Margins (NIM) and Treasury bond trading gains, which funded a +47% YoY surge in provision charges for accelerated bad-debt disposal.
Top Picks: GS maintains Buy ratings on China Construction Bank (
CCB) (clean beat, high earnings quality) and Bank of China (BOC).
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!